RSUs and Equity Explained for People Who Didn’t Study Finance
If your job offer mentioned “RSUs” and you nodded along without fully understanding what that meant, you’re far from alone. Equity compensation is one of the least explained parts of a pay package, and the tax side of it catches even experienced employees off guard. Here’s the plain-language version.
What Is an RSU, Actually?
RSU stands for Restricted Stock Unit. Strip away the jargon, and it’s essentially a promise from your employer: “if you stay employed through certain dates, we’ll give you actual shares of company stock.” Unlike stock options, there’s no purchase involved — when your RSUs vest, the shares just show up as yours, similar to receiving a bonus, except the bonus is paid in stock instead of cash.
The key word is “restricted.” You don’t own the shares yet at the time they’re granted — you only own them once they vest, meaning the time-based conditions have been met.
Vesting, Explained Simply
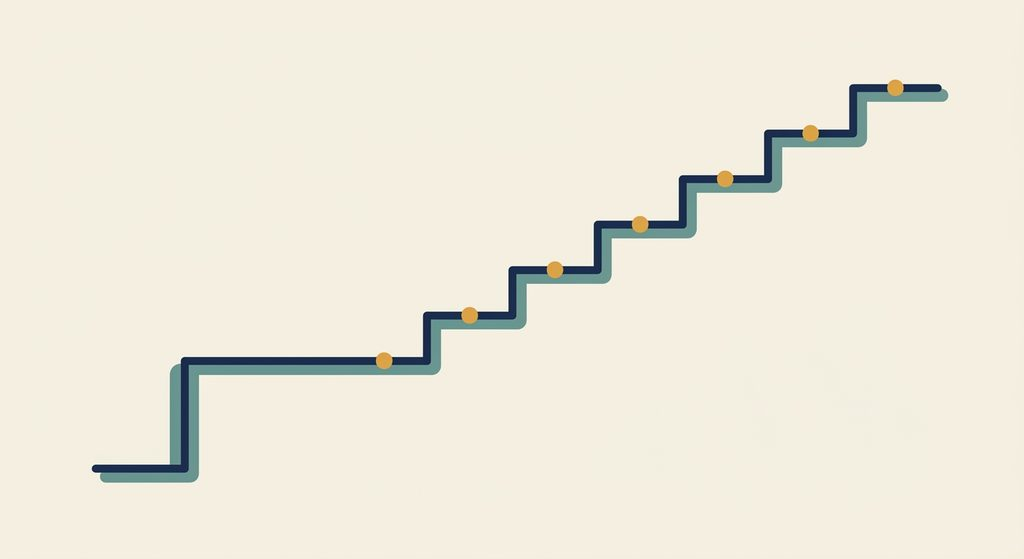
Vesting is the schedule that determines when you actually earn your shares. A common structure is a 4-year vesting schedule with a 1-year cliff — meaning you get nothing for the first year, and then a chunk vests all at once at the 1-year mark, with the rest vesting gradually (often monthly or quarterly) over the remaining three years.
What happens to unvested RSUs if you quit or get let go: in almost all cases, any shares that haven’t vested yet are simply forfeited. This is exactly why “how much equity do I have” and “how much of it is actually mine right now” are two very different questions — always ask specifically about your vested amount, not just your total grant size.
How RSUs Are Actually Taxed (The Part Nobody Explains Well)
This is where most confusion happens, so here’s the core rule: RSUs are taxed as ordinary income on the day they vest — not when you eventually sell them, and not based on what you paid for them (since you didn’t pay anything). The fair market value of the shares on your vesting date gets added to your W-2, exactly like a cash bonus would be.
That income is subject to:
- Federal income tax
- State income tax (if applicable)
- Social Security tax (up to the annual wage base, $184,500 in 2026)
- Medicare tax (1.45%, plus an additional 0.9% once your total income exceeds $200,000 single/$250,000 married)
The Withholding Gap: Why RSUs Create Surprise Tax Bills
Here’s the detail that catches nearly everyone off guard. Employers typically withhold a flat 22% supplemental rate on RSU vests. But if your actual tax bracket is higher than 22% — which is common for anyone earning a solid salary plus meaningful equity — you’ll owe more than what was withheld.
A simplified example: if you’re in the 32% tax bracket and your employer withholds at the flat 22% rate, you’re left with a 10-percentage-point gap on the entire value of your vested shares. On a $50,000 vesting event, that’s a $5,000 shortfall you’ll owe when you file — often a genuine surprise if nobody warned you this gap existed.
Sell-to-Cover: What It Means When You See It on Your Statement
Many companies handle the tax withholding through something called sell-to-cover: at vesting, the company automatically sells a portion of your newly vested shares (rather than deducting cash from your paycheck) to cover the required tax withholding, and you keep the remaining shares. This is why the number of shares that actually land in your brokerage account is often smaller than your original grant number — some were already sold to pay taxes before you saw them.
Important: sell-to-cover only handles the withholding amount, not necessarily your full tax liability — which is exactly how the withholding gap described above still catches people even when sell-to-cover is happening automatically.
RSUs vs. Stock Options: The Simple Difference
These two get confused constantly, but the distinction is straightforward:
- RSUs: you receive actual shares for free once they vest — no purchase required, no risk of the grant being “worthless” the way options can be.
- Stock options: you receive the right to buy shares at a fixed price (the strike price) in the future. If the stock price falls below your strike price, the options can become worthless. If it rises, you profit from the difference.
RSUs are now the dominant form of equity compensation at large public companies specifically because they carry less risk for employees than options — they have real value the moment they vest, regardless of how the stock performs afterward.
Should You Sell Your RSUs Immediately?
There’s no universal right answer, but here’s the framework financial advisors commonly use: concentration risk. If a large share of your net worth is tied up in your employer’s stock, you’re doubly exposed — if the company struggles, you could face both a smaller paycheck (or job loss) and a shrinking investment portfolio at the same time.
A common approach: sell vested shares soon after vesting and reinvest the proceeds into a diversified portfolio, rather than holding a large concentrated position in a single company’s stock — even a company you believe in. This isn’t about distrust in your employer; it’s about not having all your financial eggs in one basket that’s also your paycheck.
What to Actually Do With This Information
- Know your vesting schedule — mark the dates, not just the total grant size.
- Set aside extra cash for the tax gap — don’t assume the 22% withholding covers your full bill, especially if you’re in a higher bracket.
- Keep your vesting and sale records organized — grant notices, vesting statements, and brokerage 1099-B forms all matter at tax time, since brokers sometimes report incorrect cost-basis information for RSUs.
- Think about concentration risk — don’t let company stock quietly become an oversized chunk of your total net worth without a deliberate decision to keep it that way.
The Bottom Line
RSUs aren’t complicated once you understand the two things that actually matter: they’re taxed as income the moment they vest, not when you sell them, and the automatic withholding often isn’t enough to cover your full tax bill. Everything else — sell-to-cover, vesting cliffs, concentration risk — follows naturally once those two facts click.
This post reflects RSU tax rules and figures as of September 2026, including IRS Social Security wage base and Medicare thresholds for the year. Equity compensation tax situations can get complex fast — consult a tax professional for guidance specific to your grant and income situation.