529 Plans Explained: How Much Should You Actually Save?
College savings calculators have a way of making new parents panic — plug in a few numbers and suddenly you’re being told to save $500+ a month, on top of retirement, on top of everything else. Here’s a more realistic way to think about 529 plans: what they actually are, what they cover now, and how much you genuinely need to set aside.
What a 529 Plan Actually Is
A 529 plan is a tax-advantaged investment account specifically for education expenses. The core benefit: your contributions grow tax-free, and withdrawals are also completely tax-free at the federal level when used for qualified education expenses — tuition, room and board, books, and even computers. Most states also offer a state income tax deduction for contributions, on top of the federal tax-free growth.
What counts as a qualified expense has expanded significantly. Beyond college, 529 funds can now cover up to $20,000/year per student for K-12 private school tuition (increased from $10,000 starting in 2026), and — since mid-2025 — trade school and professional credentialing programs, including things like welding, cosmetology, CDL training, and CPA or bar exam prep.
How Much Does College Actually Cost Right Now?
For the 2025-2026 school year, average total costs (tuition, fees, room, and board) run roughly:
- In-state public university: ~$24,000-$31,000/year
- Out-of-state public university: ~$45,000-$51,000/year
- Private nonprofit university: ~$58,000-$65,000/year
Over a 4-year degree, that’s a wide range — anywhere from roughly $100,000 to $260,000 depending on the school type, and college costs have historically risen 4-8% annually, meaningfully faster than general inflation.
The 1/3 Rule: A Realistic Savings Target
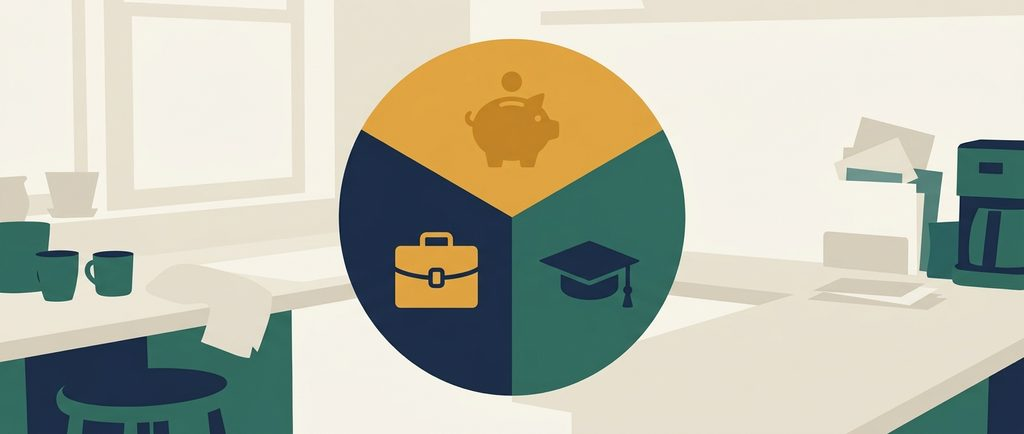
Rather than trying to save 100% of future college costs (which is what makes those calculator numbers feel so overwhelming), most financial planners recommend the 1/3 rule: aim to cover roughly one-third of projected costs through savings, with the remaining two-thirds coming from a combination of current income during the college years, scholarships, financial aid, and reasonable student loans if needed.
This reframes the goal from “save the entire cost” to “build a meaningful head start” — which is both more achievable and more honest about how most families actually pay for college in practice.
How Much Should You Actually Save Monthly?
Based on the 1/3 rule and current college cost data, realistic monthly targets look like this:
- Starting at birth, targeting in-state public: roughly $250-$400/month
- Starting at birth, targeting private university: roughly $500-$650/month
- Starting later (around age 6-10): the same goal requires significantly more per month — delaying by even a few years can increase the required monthly contribution by 15-25% per year of delay, since there’s less time for compound growth to do the work
The most important number in this whole topic isn’t the “ideal” monthly amount — it’s this: starting with even $25-$50/month today beats waiting until you can comfortably afford the “recommended” number. Time in the market matters more than the size of any individual contribution, especially in the early years.
What Families Actually Have Saved (So You Can Benchmark Yourself)
If you’re feeling behind, the actual data may be reassuring: the average 529 account balance sits around $35,000-$36,000, and total family college savings across all account types (not just 529s) averages around $42,000-$50,000. Most financial research suggests the average American family is on track to cover only about 29% of their child’s eventual college costs — meaning if you’re saving anything consistently, you’re already ahead of a meaningful share of families.
529 Contribution Limits You Should Know
- Annual gift tax exclusion: you can contribute up to $19,000 per child per year ($38,000 as a married couple) without needing to file a gift tax return
- “Superfunding” option: you can front-load up to $95,000 ($190,000 as a couple) in a single year and elect to spread it over five years for gift tax purposes — useful for grandparents or lump-sum contributions
- Aggregate lifetime limit: varies by state, but commonly falls between $400,000-$550,000 per beneficiary
What Happens to Unused 529 Funds? (The Rule That Changed Everything)
This used to be the biggest hesitation around 529 plans: what if your kid doesn’t go to college, gets a scholarship, or the account ends up overfunded? As of the SECURE 2.0 Act, there’s now a real answer.
The 529-to-Roth IRA rollover rule: you can roll over up to $35,000 over a beneficiary’s lifetime from an unused 529 into that same beneficiary’s Roth IRA, completely tax- and penalty-free. The requirements are specific: the 529 account must have been open at least 15 years, funds contributed within the last 5 years aren’t eligible, and the annual amount rolled over can’t exceed that year’s IRA contribution limit ($7,500 in 2026, or $8,600 for those 50+). The beneficiary also needs earned income at least equal to the amount being rolled over.
This means “overfunding” a 529 is no longer the risk it used to be — leftover funds have a genuine, tax-advantaged path into retirement savings instead of being stuck or facing penalties.
529 Plan vs. Roth IRA for College Savings
Some families use a Roth IRA as a supplementary or even alternative college savings vehicle, since Roth contributions (not earnings) can be withdrawn penalty-free at any time, and Roth IRA balances are invisible to FAFSA financial aid calculations — an advantage a 529 doesn’t fully share. The trade-off: Roth IRA contribution limits are much lower ($7,500/year in 2026) than what many families want to save specifically for college, and money used for college can’t be “replaced” in the account afterward the way a dedicated 529 is built to be used. Many families end up using both — a 529 as the primary vehicle, with Roth contributions supplementing it.
A Realistic Starting Framework
- Pick a target school type (in-state public is a reasonable default assumption if you’re unsure) and use current cost data, not an outdated number from when you went to school.
- Apply the 1/3 rule rather than trying to save the full projected cost.
- Start now, even with a small amount — $25-$50/month opened today beats a “someday” plan for the ideal amount.
- Check your state’s 529 tax deduction — many states offer a meaningful deduction for in-state plan contributions, which is essentially free money on top of the federal tax-free growth.
- Revisit the number every couple of years as your income, your child’s plans, and actual tuition trends become clearer.
The Bottom Line
The scary calculator number isn’t the real target — the 1/3 rule and starting early matter far more than hitting some theoretical “full cost” figure. And with the new Roth IRA rollover option, the old fear of “saving too much” in a 529 is no longer the risk it used to be. Something started today, even modestly, beats a perfect plan you keep postponing.
This post reflects 529 plan rules, contribution limits, and college cost data as of September 2026. Contribution limits, tax rules, and state-specific benefits change over time — verify current details with your state’s 529 plan or a financial advisor.