Higher Salary or Better Benefits? How to Actually Decide
You’ve got two offers on the table — or one offer and a choice to negotiate — and the numbers don’t line up cleanly. One pays more. The other has benefits that are clearly better. Comparing them by gut feeling alone almost always favors the bigger number, even when it isn’t actually the better deal.
Here’s how to make this decision with real math instead of a guess.
The Mistake Almost Everyone Makes
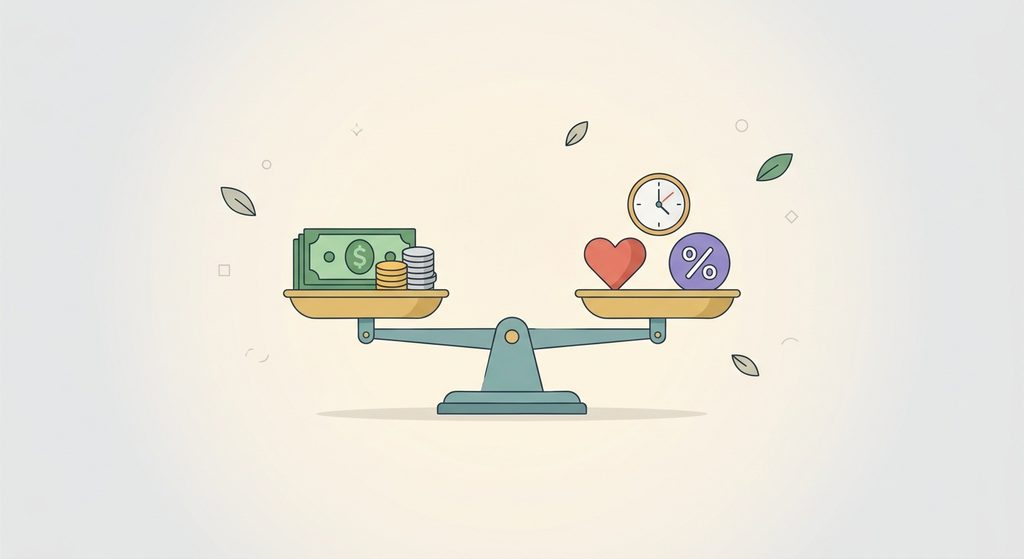
Most people compare job offers by looking at one number: base salary. But salary is only one line item in a much bigger picture — and benefits can easily be worth $10,000 to $25,000+ a year in value that never shows up as a number on an offer letter.
The fix: calculate total compensation, not just salary. That means putting a real dollar value on everything else in the package before you compare two offers side by side.
How to Put a Dollar Value on Benefits
Here’s how to translate the most common benefits into actual numbers:
- Health insurance: Compare the employer’s monthly premium contribution, not just whether insurance is offered. A difference of $400–$800/month in employer contribution is a $5,000–$10,000/year swing before you even look at deductibles.
- 401(k) match: If one employer matches 4% and the other matches 0%, that’s 4% of your salary in free money, every single year, often for as long as you stay.
- PTO: Multiply the difference in days off by your daily rate of pay. 10 extra PTO days at a $150/day equivalent is $1,500/year in value you’d otherwise have to take unpaid or not take at all.
- Remote/hybrid flexibility: Estimate commute costs saved (gas, parking, transit) plus the time value of hours back in your week — this is easy to underweight but adds up fast for the right person.
- Bonus structure: A “target bonus” isn’t guaranteed money — weight it at less than 100% of its stated value unless the company has a strong track record of paying it out in full.
The Simple Math That Settles Most Decisions
Once you’ve assigned real numbers to each benefit, add them to base salary for both offers and compare the totals — not just the headline salary number.
Example:
- Offer A: $85,000 salary, 2% 401(k) match, standard PTO, full in-office → Total estimated value: ~$87,500
- Offer B: $78,000 salary, 5% 401(k) match, 5 extra PTO days, hybrid → Total estimated value: ~$84,500 + real lifestyle value from flexibility
On paper, Offer A wins by about $3,000. But once you factor in the time and money saved by hybrid work, and the fact that a stronger 401(k) match compounds over decades, the “lower” offer can genuinely be the better long-term decision — something the raw salary number alone would never tell you.
When Salary Should Still Win
Total compensation math isn’t the whole story — sometimes the higher salary really is the right call:
- You’re carrying high-interest debt. Immediate cash flow to pay down a 20%+ APR balance usually beats a marginal benefits edge.
- You’re behind on an emergency fund. Liquidity now matters more than long-term perks you can’t access yet.
- The benefits gap is small. If the difference in benefits value is under a few thousand dollars, the simpler, higher-paying offer is often the easier call.
- Future raises are benchmarked off base salary. A higher starting salary can compound at your next job too, since many employers ask for salary history or current pay as a negotiating anchor.
Negotiate the Gap Instead of Just Picking One
If you’re deciding between two separate offers, you don’t have to simply pick the better total package — you can use one offer’s strength to negotiate the other. If Company A has the better salary and Company B has the better benefits, tell Company B the real number from Company A and ask if they can close the gap, or vice versa. Companies expect this, and it’s one of the most effective, lowest-risk negotiation moves available.
The Bottom Line
Comparing job offers by salary alone is comparing partial information. The real comparison is total compensation — salary, match, insurance, PTO, and flexibility, all converted into comparable dollar value. Once you do that math, the “obvious” choice is often not so obvious after all — and either way, you’ll be negotiating from a position of clarity instead of a guess.
This post reflects general compensation and benefits valuation guidance as of 2026. Individual situations vary — consult a financial professional for guidance specific to your offer and financial circumstances.