Index Funds vs. ETFs: What’s Actually the Difference?
If you’ve started looking into investing, you’ve probably run into both terms and wondered whether they’re two different things you have to choose between. The surprising answer is that they overlap more than most people expect.
Here’s what actually separates them, and how to pick without overthinking it.
What Is an Index Fund?
An index fund is a fund built to copy a benchmark, such as the S&P 500. It can come as either an ETF or a mutual fund. That’s the part that trips people up: “index fund” describes the strategy, while “ETF” and “mutual fund” describe the wrapper it comes in.
When people compare the two, they usually mean an ETF versus an index mutual fund, and that’s what this article covers.
Index Funds vs. ETFs: The Real Differences
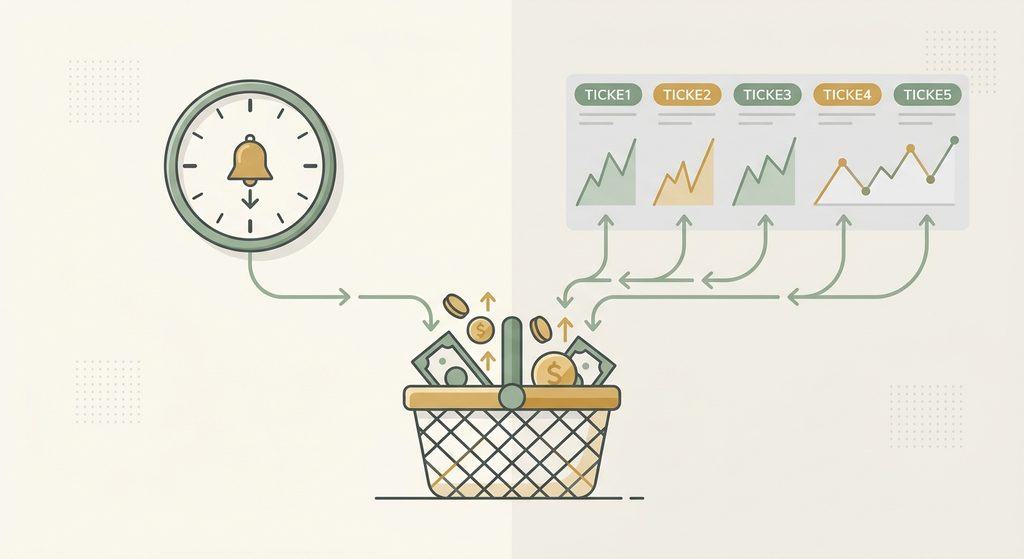
1. When you can trade. ETFs change hands all day on an exchange, so their price moves minute to minute. An index mutual fund processes every order at one price, calculated after the market closes. For long-term investors, this barely matters.
2. How you invest small amounts. With a small amount to invest, you can look for an ETF with a share price you can afford, or an index fund with no minimum investment. Many brokers also offer fractional shares, so $50 can still get you in.
3. Automatic investing. Index mutual funds have long made it easy to invest a set amount every payday. Many brokers now offer recurring purchases of ETFs too, but it varies, so check what yours supports.
4. Taxes. In a regular taxable account, ETFs usually come out ahead. When investors cash out of an index mutual fund, the manager may need to sell holdings to raise the money, which can create taxable gains for everyone in the fund. Inside a 401(k) or IRA, this difference mostly disappears.
Low-Cost Index Fund Checklist: What to Compare
Fees are the one thing worth comparing carefully.
- Expense ratio: Start here, because it keeps charging you for as long as you hold the fund. ETFs often have slightly lower expense ratios, though many index mutual funds are just as cheap. On $10,000, a 0.03% fee costs $3 a year and a 0.10% fee costs $10. That’s small, but it compounds over decades.
- Trading costs: ETFs have a bid/ask spread, which is the small gap between the buying and selling price. Index mutual funds don’t have one. Rarely traded ETFs can have wider spreads, which can cancel out their cost advantage, so stick to widely traded funds.
- Minimums and commissions: Most major U.S. brokers charge no commission on ETFs now, but confirm yours.
How to Pick the Best Index Fund (or ETF)
Skip the hunt for a single “best” fund and look for four things instead:
- A broad index, such as the total U.S. market or the S&P 500, so you own hundreds of companies at once.
- A very low expense ratio. Between funds tracking the same index, the cheaper one wins.
- A well-known provider with a long track record.
- A fit with your account and habits. A taxable account leans toward an ETF, and a retirement account or hands-off routine can work well with an index mutual fund.
Which One Should You Choose?
Lean toward an ETF if:
- You invest in a taxable brokerage account
- You want the lowest possible fee
- You’re comfortable placing a trade, even once a month
Lean toward an index mutual fund if:
- Your broker only offers automatic investing for mutual funds
- You’re investing inside a 401(k) or IRA, where taxes matter less
- You’d rather not think about trading at all
The Bottom Line
An index fund and an ETF aren’t opposites. They’re two ways to own the same thing, a basket of investments that follows a market index. For most long-term investors, the smarter move is to pick a broad, low-fee fund and automate your contributions. Which wrapper it comes in matters far less than starting and staying invested.
This post reflects general investing education as of 2026. Fund fees, features, and tax treatment vary by provider and account type. This is not investment or tax advice, so consider speaking with a licensed professional about your situation.